Accurate business valuation is the cornerstone of strategic decision-making, mergers, acquisitions, and succession planning. According to recent industry data, over 60% of small business transactions fail due to inaccurate pricing or misaligned expectations between buyers and sellers. This statistic highlights the critical need for a robust, defensible valuation methodology. The Davis Group specializes in navigating these complex financial landscapes, providing clarity where ambiguity often leads to costly errors. Understanding the nuances between different valuation approaches ensures that stakeholders can negotiate from a position of strength and factual precision.
Understanding Core Valuation Methodologies
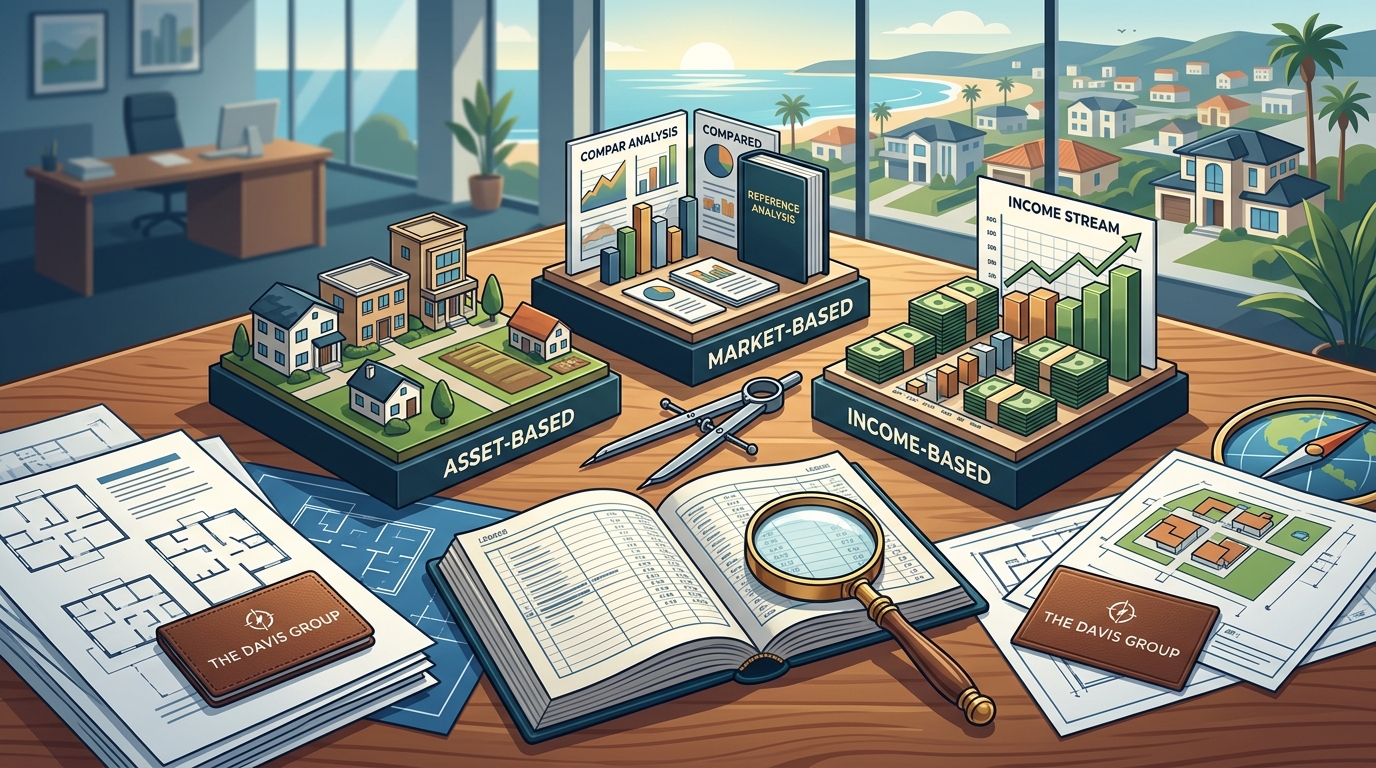
Business valuation is not a one-size-fits-all calculation. It is a disciplined process that estimates the economic value of an owner's interest in a business. The three primary approaches recognized by professional standards include the income approach, the market approach, and the asset-based approach. Each method serves a distinct purpose and provides a different lens through which to view the company's worth. (About)
The choice of method depends heavily on the industry, the company's stage of growth, and the specific reason for the valuation. For instance, a technology startup with high growth potential but low current assets will yield a vastly different result using the asset approach compared to the income approach. The Davis Group helps clients identify which methodology aligns best with their strategic goals, ensuring that the final valuation stands up to scrutiny from investors, lenders, and regulatory bodies.
The Income Approach: Discounted Cash Flow
The income approach focuses on the ability of the business to generate future economic benefits. It is based on the principle that the value of a business is the present value of its expected future cash flows. This method is particularly effective for established businesses with a history of stable or predictable earnings.
Discounted Cash Flow (DCF) Analysis
Discounted Cash Flow, or DCF, is a valuation method used to estimate the value of an investment based on its expected future cash flows. The formula requires projecting future cash flows and then discounting them back to their present value using a discount rate. This rate typically reflects the risk associated with the cash flows. A higher risk profile results in a higher discount rate, which lowers the present value of future earnings.
According to financial research, DCF is widely considered the most theoretically sound method for valuing companies with consistent cash generation. However, it is highly sensitive to assumptions. Small changes in the projected growth rate or the discount rate can lead to significant variations in the final valuation. This sensitivity makes it crucial to have rigorous financial modeling and realistic forecasting, which is a core service offered by The Davis Group's financial advisory team.
Earnings Multiples
Another variation of the income approach involves using earnings multiples. This method applies a multiple to the company's normalized earnings, such as EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization). The multiple is derived from comparable public companies or recent transactions. This approach is simpler than DCF but relies heavily on the accuracy of the comparable data.
The Market Approach: Comparable Transactions
The market approach estimates the value of a business by comparing it to similar businesses that have been sold or are publicly traded. This method operates on the principle of substitution, suggesting that a rational buyer will not pay more for a business than the cost of acquiring a similar one with equivalent potential.
Guideline Public Company Method
The Guideline Public Company Method involves analyzing financial metrics of publicly traded companies in the same industry. Key metrics include price-to-earnings (P/E) ratios, price-to-sales (P/S) ratios, and enterprise value-to-EBITDA (EV/EBITDA) multiples. These multiples are then applied to the subject company's financial data to derive a value range.
Data shows that public company multiples can fluctuate significantly based on market sentiment and macroeconomic conditions. Therefore, it is essential to adjust for differences in size, growth rate, and risk profile between the public companies and the subject business. The Davis Group leverages proprietary databases to identify the most relevant comparables, ensuring that the multiples used are accurate and defensible. For more insights on market trends, visit our market insights page.
Guideline Transaction Method
The Guideline Transaction Method looks at recent mergers and acquisitions of private companies in the same industry. This method is often considered more relevant than the public company method for private business valuations because it reflects actual transaction prices paid by strategic buyers and financial sponsors. However, data on private transactions is less transparent and harder to access.
According to industry reports, transaction multiples for private companies often command a control premium compared to public company multiples. This premium reflects the value of having decision-making power and the ability to realize synergies. Accessing reliable transaction data is a significant challenge, which is why professional valuation experts play a critical role in interpreting these metrics correctly.
The Asset Approach: Balance Sheet Reality
The asset-based approach calculates the value of a business by subtracting its total liabilities from the fair market value of its total assets. This method is essentially a balance sheet valuation. It is most appropriate for holding companies, real estate firms, or businesses that are being liquidated.
Adjusted Net Asset Value
The Adjusted Net Asset Value method adjusts the book value of assets and liabilities to their fair market values. This involves revaluing tangible assets like real estate and equipment, as well as intangible assets like patents and trademarks. The goal is to reflect what it would cost to recreate the business's asset base today.
This approach is often used as a floor for valuation, providing a minimum value for the business. It is particularly useful for companies with significant tangible assets but low earnings. However, it fails to capture the value of goodwill, customer relationships, and future earning potential. For businesses where intangible assets drive value, the asset approach may significantly understate the true worth of the company.
Comparative Analysis of Methods
Choosing the right valuation method requires a nuanced understanding of the business's characteristics and the purpose of the valuation. Below is a comparative summary of the three primary approaches.
| Valuation Method | Best For | Key Strength | Key Limitation |
|---|---|---|---|
| Income Approach (DCF) | Established businesses with predictable cash flows | Focuses on future earning potential | Highly sensitive to assumptions and discount rates |
| Market Approach (Multiples) | Companies in active M&A markets | Based on real-world transaction data | Difficulty finding truly comparable private transactions |
| Asset Approach | Holding companies, real estate, liquidation | Objective and based on tangible assets | Ignores goodwill and future earnings potential |
It is common practice to use more than one method and reconcile the results. For example, a valuation might use the DCF method to establish the core value and the Market Approach to validate it against recent industry trends. The Davis Group provides comprehensive valuation services that integrate multiple methodologies to provide a robust and defensible value range. Learn more about our business valuation services to see how we tailor our approach to your specific needs.
Key Takeaways
- Method Selection Matters: The income approach is ideal for growth-oriented businesses, while the asset approach suits asset-heavy firms.
- Market Data is Critical: Using accurate comparable transaction data is essential for the market approach to be reliable.
- Assumptions Drive DCF: Small changes in discount rates or growth projections can drastically alter DCF results.
- Reconciliation is Standard: Professional valuations often use multiple methods to triangulate a fair value range.
- Intangibles are Key: The asset approach often misses the value of brand, customer loyalty, and proprietary technology.
- Professional Expertise: Engaging a qualified valuation expert ensures compliance and defensibility.
- Strategic Alignment: The purpose of the valuation (sale, tax, litigation) dictates the appropriate methodology.
Frequently Asked Questions
What is the most accurate business valuation method?
There is no single most accurate method. The accuracy depends on the quality of the data and the appropriateness of the method for the specific business. Typically, a combination of the income and market approaches provides the most reliable result for operating businesses.
How often should a business be revalued?
Businesses should be revalued whenever a significant event occurs, such as a change in ownership, merger, acquisition, or major strategic shift. Annual valuations are also recommended for tax planning and financial reporting purposes.
What is the difference between fair market value and investment value?
Fair market value is the price at which a property would change hands between a willing buyer and a willing seller, neither being under any compulsion to buy or sell. Investment value is the value of the property to a specific investor, which may include synergies and strategic benefits not available to others.
Can a small business be valued using public company multiples?
Yes, but adjustments must be made for the lack of marketability and control. Small private companies typically trade at a discount compared to public companies due to lower liquidity and higher risk.
Why is EBITDA used in valuation?
EBITDA is used because it provides a clearer picture of a company's operational profitability by excluding non-operating expenses like interest and taxes. It allows for easier comparison between companies with different capital structures and tax environments.
What role does goodwill play in business valuation?
Goodwill represents the intangible value of a business, such as brand reputation, customer relationships, and employee expertise. It is calculated as the excess of the purchase price over the fair value of identifiable net assets. Goodwill is a significant component of value for service-based and technology companies.
How long does a professional valuation take?
The timeline varies based on the complexity of the business and the scope of the engagement. A standard valuation for a small to mid-sized business typically takes four to eight weeks to complete, including data collection, analysis, and report drafting.
Contact The Davis Group
Navigating the complexities of business valuation requires expertise, precision, and a deep understanding of market dynamics. The Davis Group is dedicated to providing clear, actionable insights that empower your strategic decisions. Whether you are preparing for a sale, planning succession, or seeking financing, our team is here to guide you.
Take the next step in securing the true value of your business. Contact The Davis Group today to schedule a consultation and discover how we can help you achieve your financial goals.